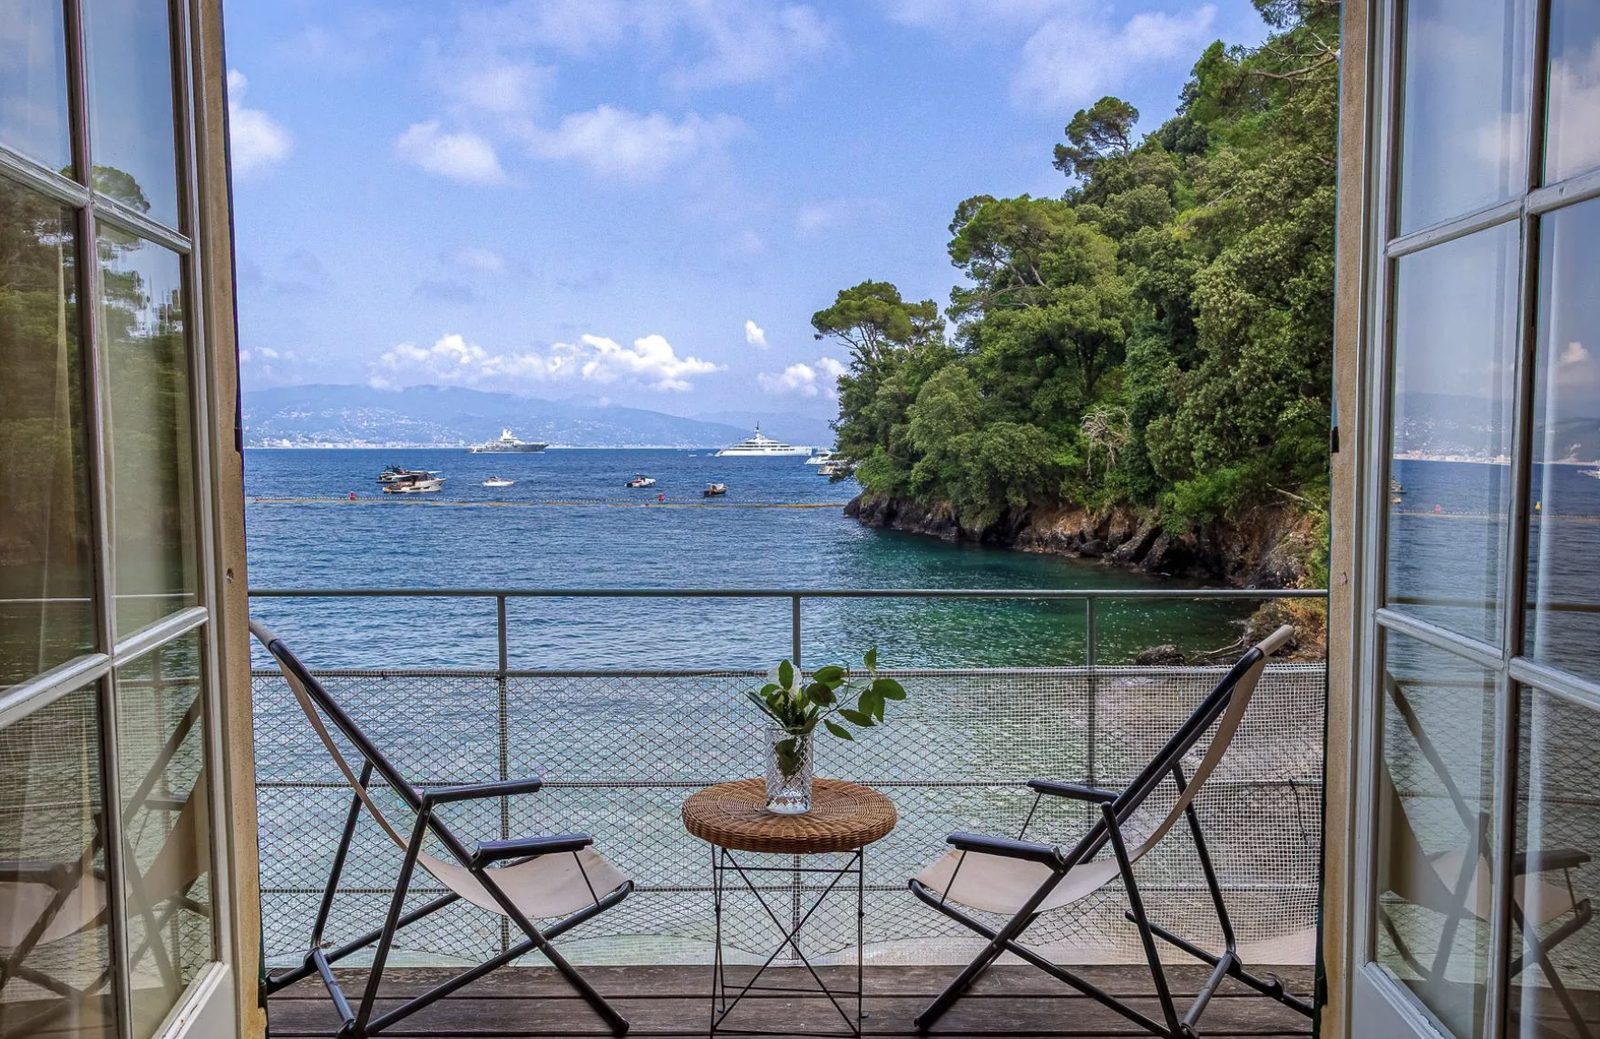
A three-bedroom home in Portofino, Italy.
Opening an Italian Bank Account as an American: What You Actually Need
September 2026
Quick Answer
You don't need an Italian bank account to close on a property, but you'll want one soon after for IMU, utilities, condominium fees, and rental income. The real obstacle isn't paperwork, it's finding a bank willing to take you: FATCA reporting requirements lead some smaller Italian banks to decline American applicants outright. Larger banks with international desks, plus digital options like N26 and Wise, are where most American buyers actually end up.
Every guide to buying property in Italy eventually mentions that you'll need an Italian bank account, then moves on without explaining what that actually involves. The mechanics aren't complicated. The friction is that American citizenship itself makes some Italian banks reluctant to open an account for you at all, a fact almost nobody explains until you're already standing at a branch counter being told no.
This is the piece that usually sits between the notaio guide and the tax guides on every American buyer's reading list: not because it's hard, but because nobody tells you it's a separate step with its own separate obstacle.
Why You Actually Need One
The property purchase itself doesn't require an Italian account. Deposit and closing funds are commonly wired directly from a US account through the notaio's escrow process. What does require an Italian account, in practice, is everything that happens after closing: IMU property tax payments, condominium fees (spese condominiali), utility direct debits, and, if you rent the property, collecting rental income in euros without a foreign-transaction fee on every payment. Attempting to run all of this through a US account and international wire is not illegal, just consistently more expensive and slower than most owners are willing to tolerate for more than a year or two.
The FATCA Friction Nobody Mentions
| Factor | What It Means for You |
|---|---|
| FATCA reporting requirement | Italian banks must identify US persons among their account holders and report account details to the Agenzia delle Entrate, which shares them with the IRS annually |
| Bank's compliance cost | Each US-person account carries ongoing reporting overhead the bank must absorb, regardless of account size |
| Practical result | Some smaller regional banks decline to open new accounts for US citizens rather than build out FATCA compliance for a small number of clients |
| Where this doesn't apply | Larger national banks with dedicated international or private banking desks handle US clients routinely and rarely decline on this basis |
This is the single most common surprise American buyers report: walking into a small-town branch near their new property, being asked for a W-9, and then being told the bank doesn't accept US citizens as retail customers. It isn't personal and it isn't about your creditworthiness. It's a standing policy at the branch or institution level. The fix is simply choosing the right bank from the start rather than the nearest one. Full US reporting obligations that follow from opening any foreign account are covered in the FBAR and FATCA guide.
Which Banks Actually Work With Americans
| Option | Typical Experience for Americans | Branch Visit Required |
|---|---|---|
| Intesa Sanpaolo | Italy's largest bank; international and private banking desks in major cities routinely handle US clients | Yes |
| UniCredit | Second-largest bank; similar international client capacity, especially in Milan, Rome, and larger regional cities | Yes |
| Smaller regional and cooperative banks | Mixed and often unfavorable; some outright decline US citizens rather than build FATCA compliance infrastructure | Yes, if accepted at all |
| N26 | German digital bank operating in Italy; accepts US persons in many cases, opened largely online | Often no |
| Wise | Multi-currency account with an Italian IBAN; not a full bank account but covers receiving euros and paying local bills for many owners | No |
Most American buyers land in one of two patterns: a full account at a major national bank with international banking experience, or a digital-first account like N26 or Wise used alongside occasional wires from the US account, particularly in the first year or two of ownership before a full Italian relationship is worth the effort.
Documents to Bring
- Valid US passport, the primary identity document for any Italian bank.
- Codice fiscale, the Italian tax ID number required before almost any financial or legal transaction in Italy. See the codice fiscale guide if you don't already have one.
- Proof of Italian address, which can be the property purchase agreement, a rental contract, or a recent utility bill in your name.
- Completed W-9 form, which the bank needs on file for its FATCA reporting obligations from day one.
- Proof of income or source of funds, which some banks request for the initial deposit, particularly at larger institutions with anti-money-laundering compliance standards.
Timeline and What It Costs
Budget one to two branch visits and one to three weeks for a traditional account to become fully operational, including debit card issuance and online banking setup. Most major banks charge a modest monthly account maintenance fee, typically in the 5 to 15 EUR range, though fee structures vary and some offer reduced rates for non-resident or expat account packages. Digital options like N26 and Wise can be operational within days, often with no monthly fee for a basic tier, but come with lower transaction limits and less capacity for in-person problem-solving if something goes wrong.
What to Do Before You Fly Over
Get your codice fiscale sorted first, ideally through the Italian consulate in the US before you travel, since almost nothing else can proceed without it. If you already know which bank you want, some larger banks allow you to schedule an appointment in advance and confirm document requirements by email, which saves a wasted trip if a specific branch turns out not to accept US clients. If your timeline is tight around a closing, opening a Wise account before you travel gives you a working Italian IBAN for smaller payments while the full bank account process plays out.
Navigating the Banking Step?
Peter can point you toward banks with a track record of working with American clients in your target region, alongside the rest of the buying process.
Submit an Inquiry Full Buying Process GuideFrequently Asked Questions
Do I need an Italian bank account to buy property in Italy?
Not strictly for the deposit and closing funds, which can be wired directly from a US account through the notaio. But nearly every buyer opens one shortly after, since IMU property tax, utility bills, condominium fees, and rental income all run through an Italian account far more easily than through a US one.
Why do some Italian banks refuse American customers?
FATCA requires foreign banks to identify US account holders and report their account details annually to the IRS, or face a 30% withholding penalty on certain US-source payments to the bank itself. Some smaller Italian banks decide the compliance burden isn't worth it for a small number of American clients and simply decline to open new accounts for US citizens.
What documents do I need to open a bank account in Italy?
A valid US passport, your codice fiscale, proof of an Italian address (a purchase agreement, rental contract, or utility bill), and a W-9 form for FATCA purposes. Some banks also want proof of income or the source of funds for the initial deposit.
Can I open an Italian bank account before I travel to Italy?
Traditional Italian banks generally require an in-person visit to a branch to open an account, since it involves in-person identity verification. Digital-first options such as N26 and Wise can be opened remotely in some cases and are commonly used by American buyers as a bridge before or alongside a traditional Italian account.
Do I have to report my Italian bank account to the IRS?
Yes. An Italian bank account is a foreign financial account subject to FBAR reporting if your combined foreign account balances exceed 10,000 USD at any point in the year, and potentially Form 8938 reporting under FATCA depending on your filing status and total foreign asset value. Full detail is in the FBAR and FATCA guide.